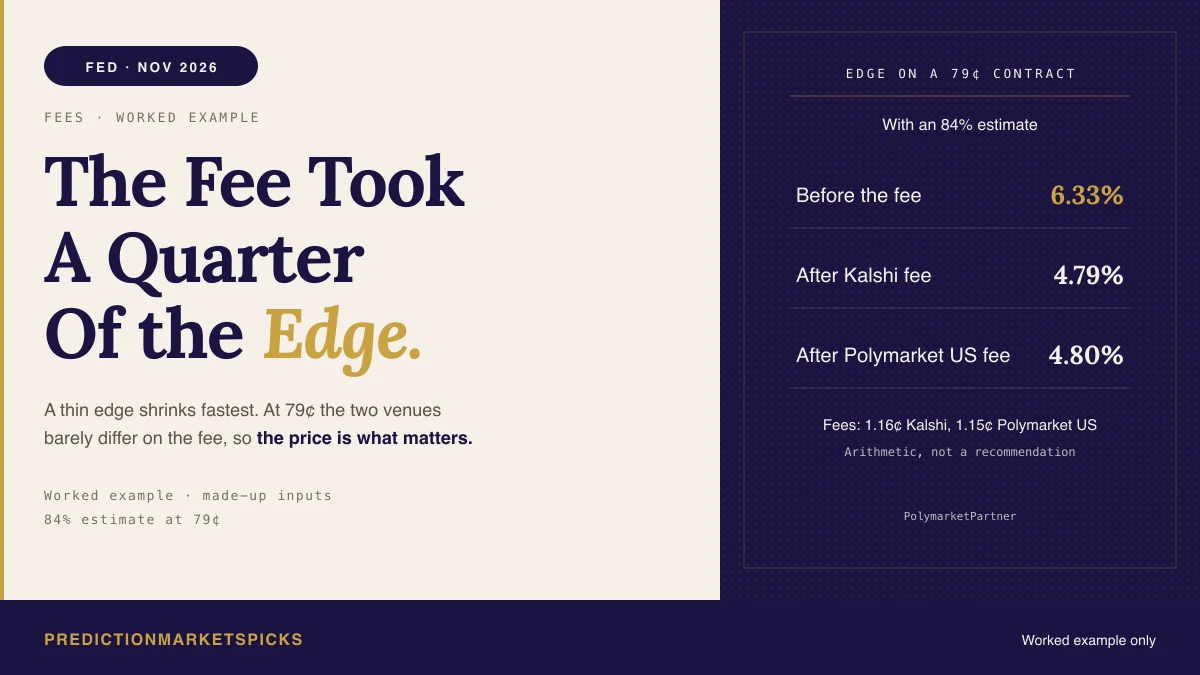
The fee on a Fed contract looks small until you put it next to the edge. Here's a worked example with made-up inputs: the contract is 79¢ and you put the true chance at 84%.
| Kalshi | Polymarket US | |
|---|---|---|
| Price | 79¢ | 79¢ |
| Taker fee | 1.16¢ | 1.15¢ |
| All-in cost | 80.16¢ | 80.15¢ |
| Edge before the fee | 6.33% | 6.33% |
| Edge after the fee | 4.79% | 4.80% |
The fee took about a quarter of the edge. That's the first takeaway: a thin edge shrinks fastest, so a position that looks fine on the price can fail once costs are in.
The second is that the two fee schedules barely differ at this price. The gap between venues is about a hundredth of a cent, so the price each one shows matters far more than whose schedule you're on. A single cent of price difference outweighs the fee difference many times over.
Run the Fed contract numbers yourself
The EV calculator now has a venue selector, and the Kelly calculator carries the same row through to position size. For the exact fee on a fill, use the Kalshi fee calculator or the Polymarket US fee page.
An AI agent gets the same numbers from calculate_ev. Pass venue for one venue, or venuePrices with each venue's price, and it returns the edge after each fee and names the best one. Novig is sports-only, so it isn't part of a Fed comparison.
Live prices are on the Fed rate tracker, and how Kalshi settles these contracts covers the rules. This is arithmetic, not a recommendation.
PolymarketPartner: PredictionMarketsPicks is a paid Polymarket partner.
Trade responsibly.